Jumbo & Proprietary Reverse Mortgages in California
Reverse Your Thinking® · Mathius Marc Gertz, MBA, AFC®, CDLP®, CREV, CAPS
Your Home Is Worth Millions. Your Reverse Mortgage Options Should Match.
Your home in California is worth millions, and your income does not come close to matching it. You have looked into a standard reverse mortgage, and the numbers never seem to reach far enough.
You may also be carrying an older fear, the one about signing over the deed and losing the house for good.
That fear is understandable, but it is not true anymore. A modern reverse mortgage, including a jumbo or proprietary reverse mortgage in California, still leaves your name on the title.
Mathius Marc Gertz can compare different proprietary lenders and a dozen reverse mortgage companies for every client. If a standard HECM is the better fit, or if a reverse mortgage is the wrong fit, he will say so.
Homeowners who came to him with the same worries you have are now living on income from their house, without a monthly mortgage payment and without giving up ownership.
Tell Marc what your home is worth and what you actually need it to do for you, and he will find the program built for that.
| NMLS #1125159 · DRE #01999021 | AFC® Fee-Based Counselor | 12 Reverse Lenders Compared | CDLP® · CREV · CAPS |
The Facts Behind Today’s Reverse Mortgage
Start Your Reverse Mortgage Evaluation
call us today
310-447-5266Why California’s Highest-Value Homes Need Their Own Reverse Mortgage
A standard Home Equity Conversion Mortgage (HECM) is federally insured, and for 2026 the FHA will only count the first $1,249,125 of your home’s value when it calculates what you can borrow. If your California home is worth $2 million, $4 million, or more, that ceiling leaves most of your equity untouched.
A jumbo, or proprietary, reverse mortgage in California is designed for that gap. It uses your home’s actual value, not a capped figure. Like an HECM, it is non-recourse. You, your estate, and your heirs will never owe more than the home is worth, and the title stays in your name for as long as you own it.
There is no required monthly mortgage payment on either program. Some proprietary options are also available starting at age 55, seven years earlier than the 62 minimum for a standard HECM, which opens the door for younger retirees who are asset-rich and cash-poor.
The details of how a specific program is structured are worth a real conversation, not a page of fine print.
Why Compare Lenders Instead of Calling Just One
Every proprietary reverse mortgage lender designs its own program, with its own loan limits, its own rates, and its own age minimums. Call one lender directly and you get one answer, built around what that lender offers, not necessarily what you need.
Marc works across 12 reverse mortgage companies, including seven that offer proprietary and jumbo programs. He compares them for you before recommending anything. As an Accredited Financial Counselor, he can also offer fee-based counseling separate from any lender relationship, so the advice you get is not tied to which program pays him.
If a standard HECM turns out to be the better fit for your home and your income, he will tell you that directly, even though a jumbo loan is often the larger transaction. Attorneys, CPAs, and financial planners who send clients to Marc expect that honesty. So should you.
Real Results for High-Value California Homes
These are real, anonymized examples from clients we have worked with directly.
- A 91-year-old homeowner in Venice, California, held a home worth $1.75 million and received a $1.1 million jumbo reverse mortgage.
- An 88-year-old retired designer in Beverly Hills accessed $2.2 million against a $4.5 million home.
- A couple in their late 60s in Saratoga, California, received $950,000 on a $2 million home.
- A Beverly Hills client structured a jumbo reverse mortgage that set aside $1,000,000 toward monthly income, with the appraisal coming in at full value.
Individual results vary by home value, age, and program. Not all customers will qualify, and prior results do not guarantee a similar outcome for your situation.
Built for Beverly Hills, Santa Monica, and the Rest of Los Angeles County
Jumbo and proprietary reverse mortgages make the most sense where home values run well past the FHA limit. That describes much of Los Angeles County, from Beverly Hills and Santa Monica to Malibu, Calabasas, and Encino. We also work with clients throughout Los Angeles and Inglewood, matching each homeowner to the program that fits their specific home value and goals.
If your home sits in Beverly Hills or Santa Monica, two of the areas where this program comes up most often, see our pages on reverse mortgages in Beverly Hills and reverse mortgages in Santa Monica for what a jumbo program can mean in your neighborhood. For a broader look at how reverse mortgages work across the state, our California reverse mortgage guide covers the basics, and our Los Angeles and Inglewood pages cover more of the region.
Fact vs. Fiction: Jumbo and Proprietary Reverse Mortgages
Here are some things you should know about jumbo and proprietary reverse mortgages in California:
Fiction: Jumbo and proprietary reverse mortgages are riskier because the government does not back them.
Fact: They are still non-recourse loans. You, your estate, and your heirs will never owe more than the home’s value, even without FHA insurance behind the loan.
Fiction: You have to be 62 to qualify, just like a standard HECM.
Fact: Some proprietary programs accept borrowers starting at 55, based on the youngest borrower’s age and the home’s value.
Fiction: A high-value home is too complicated for a reverse mortgage to make sense.
Fact: High-value homes are exactly where these programs do their best work, because they are built to use the equity a standard HECM has to leave on the table.
Let’s Reverse Your Thinking® about what your California home can do for you.
Jumbo and Proprietary Reverse Mortgage FAQ
Can I get a jumbo reverse mortgage before I turn 62?
Some proprietary programs accept borrowers as young as 55, unlike a standard HECM, which requires the youngest borrower on title to be at least 62. Eligibility still depends on your home’s value, your equity, and the specific program.
Do I still own my home with a jumbo reverse mortgage?
Yes. You keep the title, and the loan is non-recourse, meaning you, your estate, and your heirs will never owe more than the home is worth when the loan is repaid.
What does it cost to find out if I qualify for a jumbo mortgage?
Nothing. A review of your home value, your age, and your goals against the jumbo and proprietary programs available in California is free, with no obligation to move forward.
A Smarter Way to Use Your Home Equity
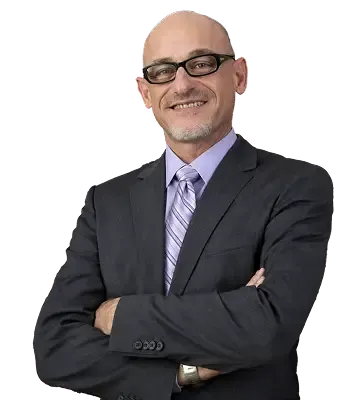
Let’s Find the Right Program for Your California Home
You do not need to be a financial expert to have this conversation. Tell Marc your home’s value, your age, and what you want your equity to do for you. He can walk you through the jumbo and proprietary options that may be right for you.
Call (310) 447-5266 for a free, no-pressure review of your proprietary reverse mortgage options, or request a consultation online.
This is for information purposes only and is not an offer to enter into an agreement. This is not a commitment to lend or extend credit. Not all customers will qualify. Information, rates, and programs are subject to change without notice and are subject to credit and property approval. Mathius M. Gertz, NMLS #1125159, DRE #01999021. SayWhyNot, Incorporated, NMLS #2161957, DRE #02139767. Loans arranged through E Mortgage Capital, Inc., NMLS #1416824, Equal Housing Lender.
For licensing information, visit nmlsconsumeraccess.org.